What is Buy-to-Let Debt Consolidation
Managing multiple debts tied to your buy-to-let properties can feel overwhelming. With different interest rates and repayment terms across loans, staying on top of them can be challenging. Debt consolidation offers a way to simplify this by merging all your debts into one manageable loan.
By consolidating, you streamline your repayments into a single monthly payment. This often reduces the stress of managing various deadlines and amounts. In some cases, it can also result in lower monthly payments, depending on the terms of the new loan.
Debt consolidation also provides an opportunity to focus on your investment goals. By eliminating the hassle of juggling multiple debts, you can better plan improvements, expand your portfolio, or simply improve cash flow for better financial stability.
How Buy-to-Let Debt Consolidation Works
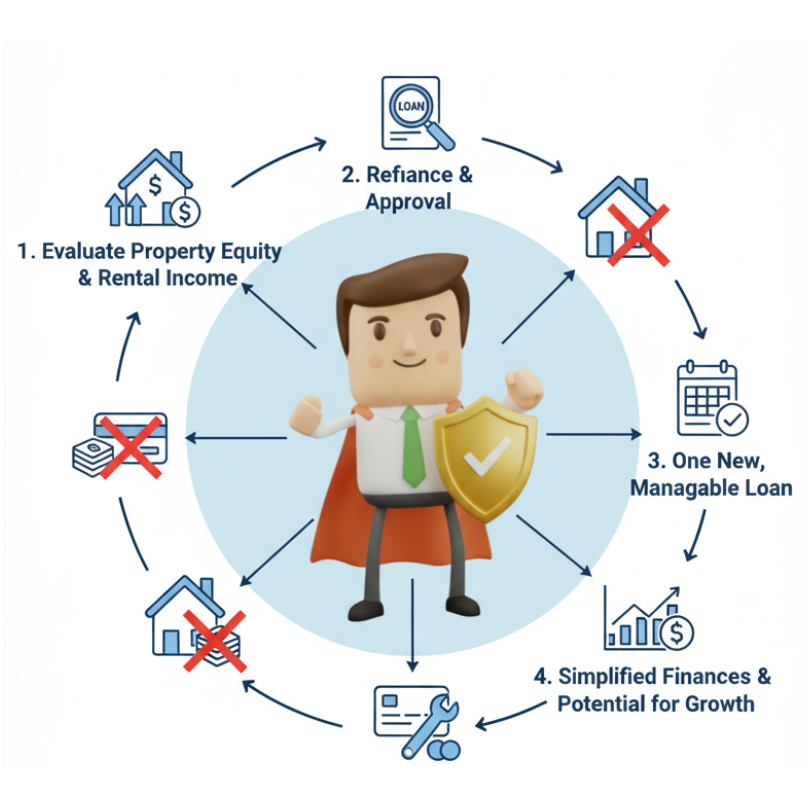
Debt consolidation works by refinancing your existing buy-to-let mortgages and associated debts into one loan. The first step is evaluating the equity in your properties, which determines how much you can borrow. Rental income is also reviewed to ensure it supports the new repayment terms.
Once approved, the new loan is used to pay off your existing debts, leaving you with one manageable monthly payment. This can make budgeting more straightforward and may free up funds for other purposes, such as property improvements or new investments.
However, while consolidation can reduce monthly payments, extending the loan term may mean paying more in interest overall. It's crucial to weigh the immediate benefits against the long-term costs to ensure it aligns with your financial objectives.
Why Work with a Mortgage Broker for Debt Consolidation
A mortgage broker specialising in buy-to-let debt consolidation can provide valuable guidance. They start by reviewing your debts and financial situation to identify the best lenders and products suited to your needs.
With access to a wide range of lenders, brokers can often secure more competitive rates or tailored deals. Their expertise helps navigate complex terms, ensuring your consolidation process is as smooth and beneficial as possible.
Brokers also assist with the paperwork and application process, saving you time and effort. They'll help you understand how consolidation impacts your cash flow and long-term investments, offering strategies to maximise your portfolio's profitability. With their support, you can restructure your debts with confidence and focus on future growth.
Frequently Asked Questions
FAQs about Buy-to-Let Debt Consolidation
What is buy-to-let debt consolidation?
How does buy-to-let debt consolidation work?
What are the benefits of consolidating buy-to-let debts?
Am I eligible for buy-to-let debt consolidation?
What types of debts can be consolidated in a buy-to-let portfolio?
How do lenders assess buy-to-let debt consolidation applications?
Can I use a buy-to-let debt consolidation loan to purchase new properties?
What are the potential risks of consolidating buy-to-let debts?
How long does the buy-to-let debt consolidation process take?
Are there any fees associated with buy-to-let debt consolidation?
Can I release equity from my properties through debt consolidation?
How can a mortgage broker assist with buy-to-let debt consolidation?
For more detailed information, speak to one of our mortgage specialists to assess your specific situation.
Client Testimonial
"Trying to sort out my Buy to Let debts on my own was a nightmare, there were too many moving parts, too many lenders saying different things. I wasn't even sure if consolidation was possible without disrupting my tenants or refinancing every property. One of my friends recommended calling Power Mortgages.
I spoke with Manny; he didn't just give me options; he gave me clarity. He took what I thought was a messy situation and broke it down into something manageable. What really stood out was how he tailored everything to my long-term goals, not just the numbers in front of him. It felt like working with someone who actually understood the business side of being a landlord."
Sanjay B