Buy-to-Let Mortgages
Tailored funding solutions for property investors.
If you're planning to invest in property and earn rental income, a Buy to Let mortgage is an essential step in making it happen.
A specialist mortgage adviser can guide you through the process, helping you find the most suitable lenders, secure competitive rates, and navigate the specific criteria involved with Buy to Let lending, making the journey smoother from start to finish.
Understanding what a Buy-to-Let Mortgage is
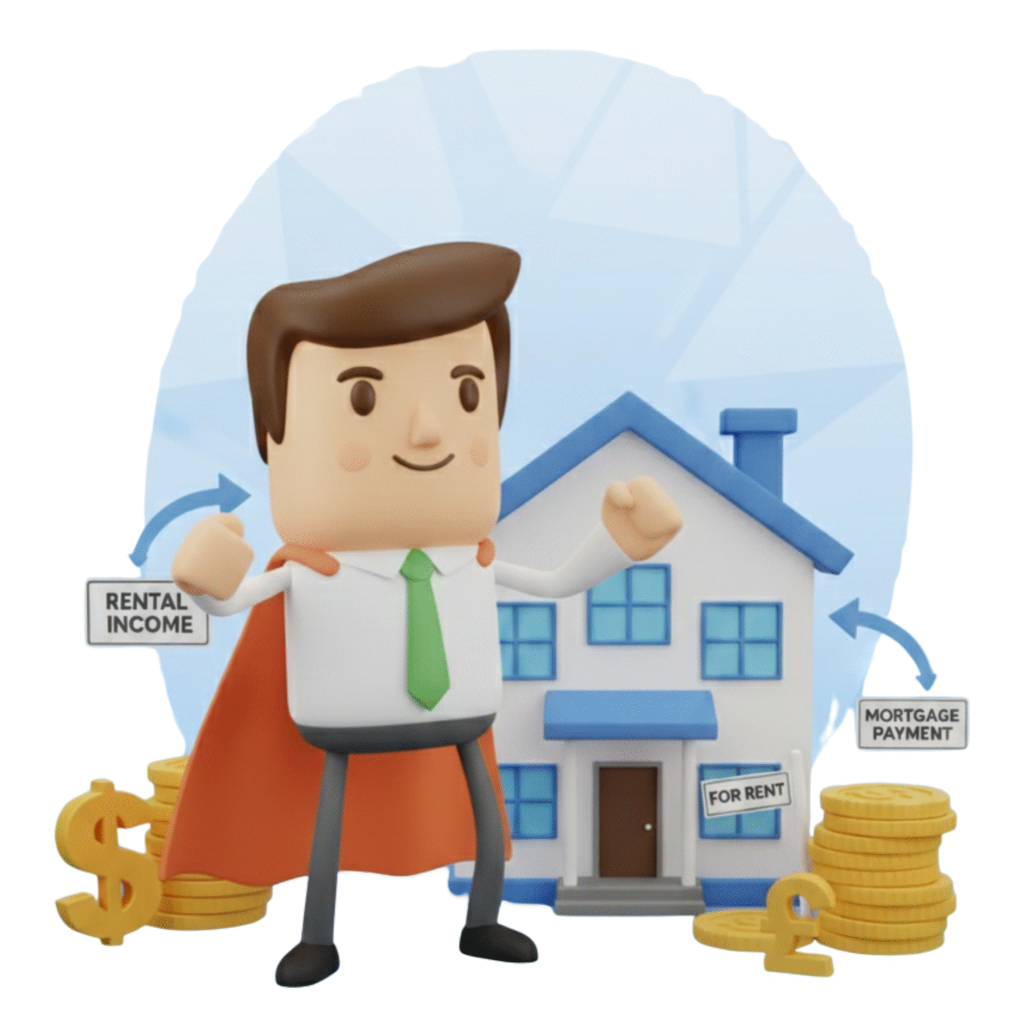
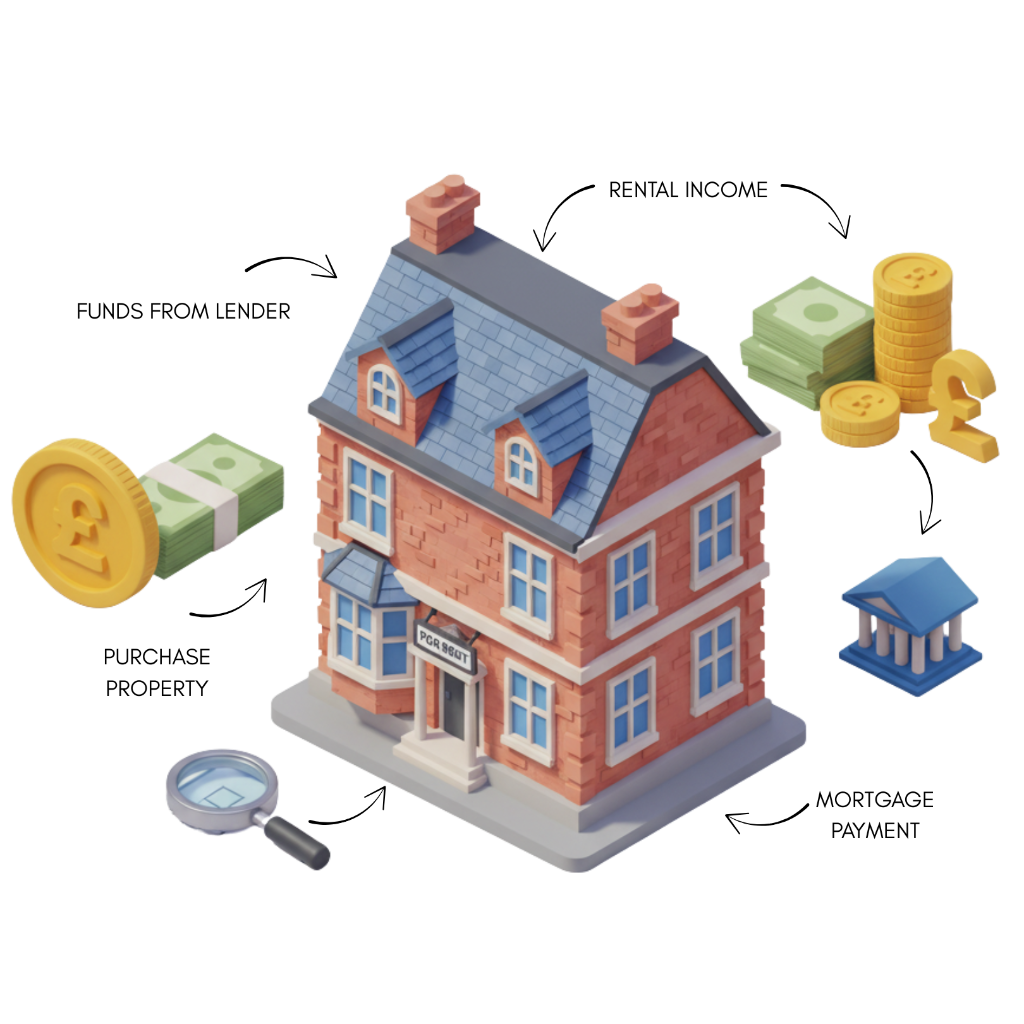
A Buy-to-Let (BTL) Mortgage is a specialist loan designed for landlords purchasing a property to rent out. Unlike residential mortgages, which are for buyers acquiring a home to live in, Buy-to-Let Mortgages cater specifically to property investors and landlords.
Typically, Buy-to-Let mortgages are offered on an interest-only basis, helping to keep monthly repayments low. Lenders usually require a deposit of at least 20%, as they provide funding for up to 80% of the property's value.
Because Buy-to-Let mortgages are considered higher risk due to the reliance on rental income, they fall into the category of specialist lending. As a result, they can be more challenging to qualify for than standard residential mortgages.
How Buy-to-Let Mortgages work
Buy-to-Let Mortgages provide landlords with the funding needed to purchase or remortgage investment properties. Whether you're a first-time landlord or a seasoned investor, these loans are tailored to help you achieve your property goals.
Here are the types of landlords we support at Power Mortgages:
- First-Time Landlords: Securing their first Buy-to-Let mortgage with expert guidance.
- Existing Landlords: Looking to refinance or grow their portfolio.
- Portfolio Landlords: Managing multiple properties with customized lending options.
- Refinancing: Securing better rates or adjusting terms for improved cash flow.
- Capital Raising: Leveraging equity to fund new property purchases or for any other legal purpose.
- Residential to Buy-to-Let: Transitioning from personal use to rental income.
Important Considerations for Buy-to-Let Mortgages
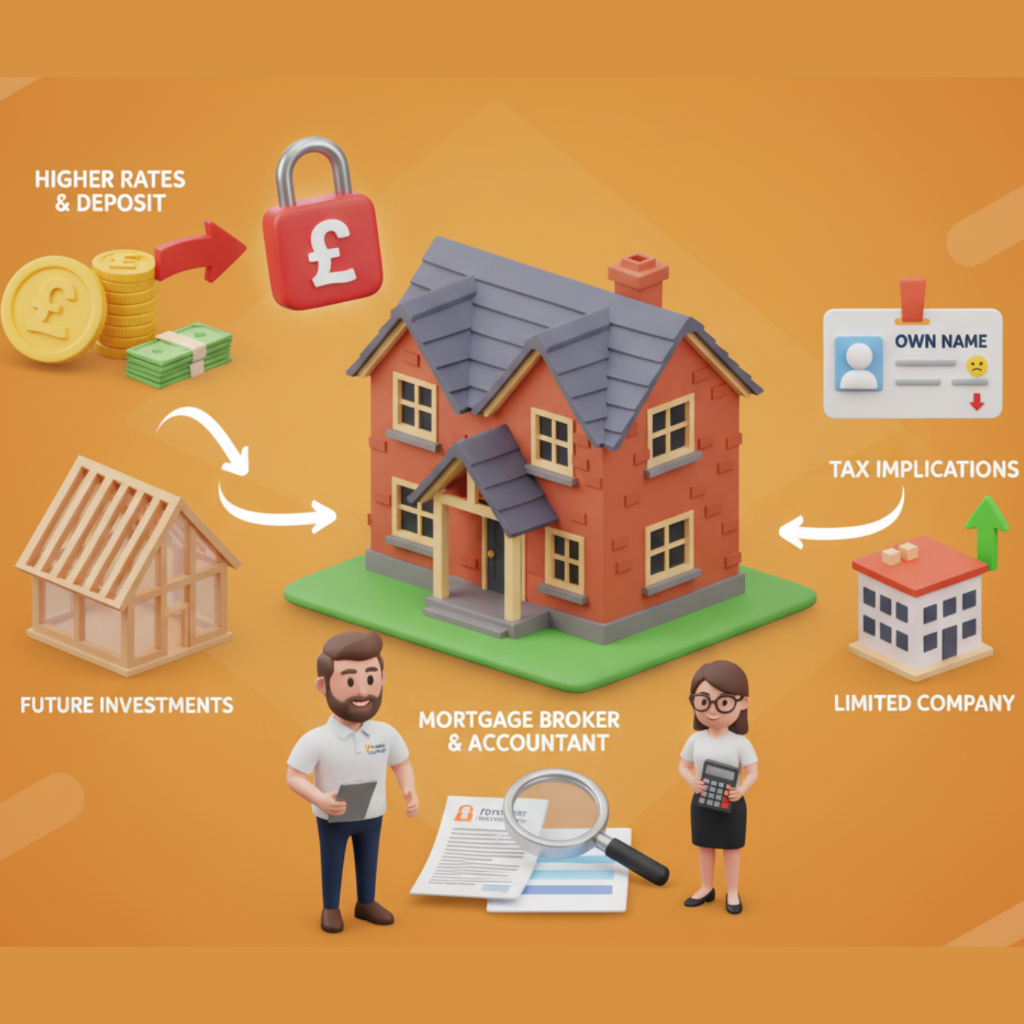
Buy-to-Let Mortgages rates are typically higher than residential mortgage rates, and lenders often require a larger deposit. Many landlords choose to remortgage their existing properties to raise funds for future investments.
Working with an experienced mortgage broker and accountant is crucial to getting the most from your Buy-to-Let Mortgage. For example, the decision to purchase in your own name or through a limited company can have significant tax implications.
At Power Mortgages, we specialise in helping landlords navigate these complex decisions, ensuring you have the right funding and expert advice to build a successful property portfolio.
How a Buy-to-Let Mortgage Broker
Can Help You Secure the Best Deals
As a Buy-to-Let Mortgage broker Power Mortgages specialises in guiding landlords, whether seasoned investors or first-time landlords through the process of finding and securing the most suitable mortgage deals for their property investments. As Buy-to-Let mortgages are a specialist area of lending, working with a broker who has expert knowledge of criteria and options is essential for success.
At Power Mortgages, our experienced team takes the hassle out of the process by managing everything from start to finish. Here's how we can help you:
Buy-to-Let Purchases
Simplifying the process of financing new investment properties.
Buy-to-Let Remortgages
Assisting you in refinancing to reduce costs or release equity.
Capital Raising
Releasing funds to expand your portfolio or invest further.
HMO Limited Company Mortgages
Providing tailored solutions for Houses in Multiple Occupation.
Limited Company Mortgages
Providing specialist advice on company structures and Limited Company Mortgages.
New Fixed Rate Deals
Securing competitive rates to keep your costs predictable.
Auction Finance
Arranging fast financing for time-sensitive auction purchases.
Bridging Loans
Offering short-term funding to ensure seamless property transactions.
Complex Buy-to-Let Cases
Delivering expert solutions for unique or challenging scenarios.
Many landlords choose Power Mortgages not just for our expertise but for the ongoing support we provide. From reviewing your portfolio to refinancing for improved terms, we're here to ensure your investments perform at their best.
Partner with Power Mortgages today to secure the best deals and make the most of your Buy-to-Let ventures.
Frequently Asked Questions
Frequently asked questions about Buy-to-Let (BTL) mortgages
How does a Buy-to-Let mortgage differ from a residential mortgage?
What deposit is required for a Buy-to-Let mortgage?
Can first-time buyers obtain a Buy-to-Let mortgage?
How is the loan amount determined for a Buy-to-Let mortgage?
Are Buy-to-Let mortgages offered on an interest-only basis?
What are the tax implications of a Buy-to-Let property?
Can I use my personal income to support a Buy-to-Let mortgage application?
Do I need a specific type of property insurance for a Buy-to-Let property?
Can I live in my Buy-to-Let property?
What fees are associated with Buy-to-Let mortgages?
Is there an age limit for obtaining a Buy-to-Let mortgage?
Can I get a Buy-to-Let mortgage through a limited company?
What is a House in Multiple Occupation (HMO), and can I get a mortgage for one?
How does remortgaging a Buy-to-Let property work?
What is the stress test in Buy-to-Let mortgages?
Can I switch my residential mortgage to a Buy-to-Let mortgage?
Are there restrictions on the type of property for a Buy-to-Let mortgage?
Do I need a tenancy agreement for my tenants?
Can I use projected rental income from Airbnb or short-term lets for a Buy-to-Let mortgage?
What happens if my property is vacant and I can't meet mortgage payments?
Can I apply for a Buy-to-Let mortgage if I have bad credit?
Do I need an existing property portfolio to get a Buy-to-Let mortgage?
How long does it take to get a Buy-to-Let mortgage approved?
Are there fixed-rate Buy-to-Let mortgages available?
Can I refinance my Buy-to-Let mortgage to release equity for another property purchase?