Buy-to-Let Mortgage Declined
Having your Buy-to-Let mortgage application declined can be frustrating and leave you uncertain about your next steps.
A specialist adviser can review your circumstances, identify the reasons for the decline, and guide you towards alternative solutions to secure the funding you need.
Why Your Buy-to-Let Mortgage Application May Be Declined
One of the most common reasons for a declined application is poor credit. Lenders heavily rely on your credit score to assess whether you're a reliable borrower. A low score can raise concerns about your ability to manage debt.
Lenders also need to ensure the property you're looking to buy will generate enough rental income to cover the mortgage payments. If the property doesn't meet the required income threshold, it could result in rejection.
A small deposit can also hinder your chances of getting approved. Lenders prefer larger deposits as they reduce their risk, especially in Buy-to-Let mortgages. The bigger the deposit, the more attractive your application becomes to lenders.
How to Improve Your Chances of Getting Approved for a Buy-to-Let Mortgage
If your application has been declined, check your credit report to identify any issues. Improve your score by paying off debts or addressing any discrepancies on your record.
Ensure that the property you want to buy can generate consistent rental income. Research high-demand areas and focus on properties that will attract tenants easily.
The more you can save for a deposit, the better your chances of getting approved. A larger deposit reduces the lender's risk and demonstrates your commitment to the investment.
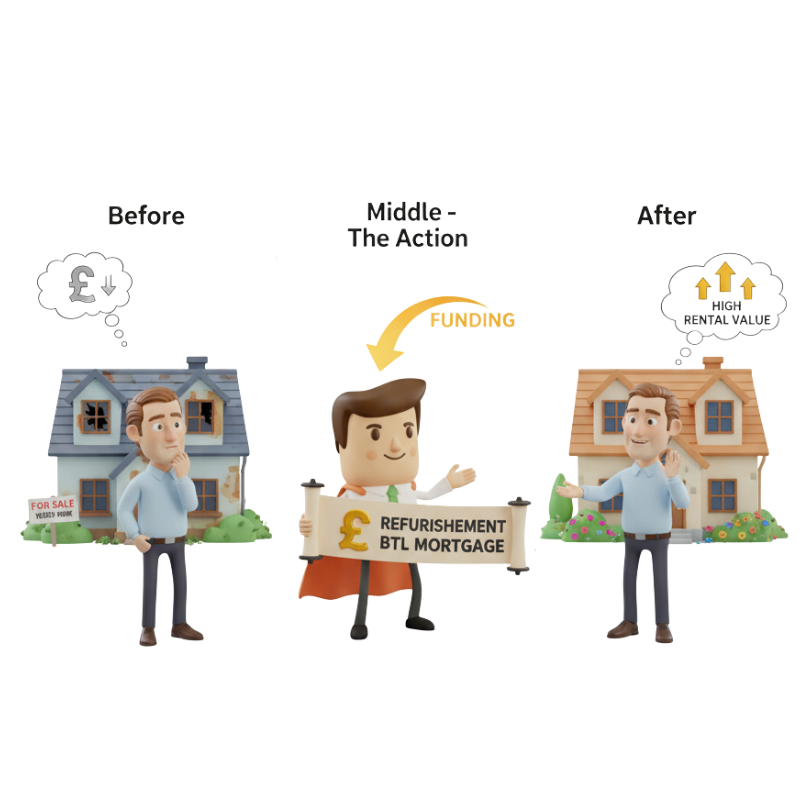
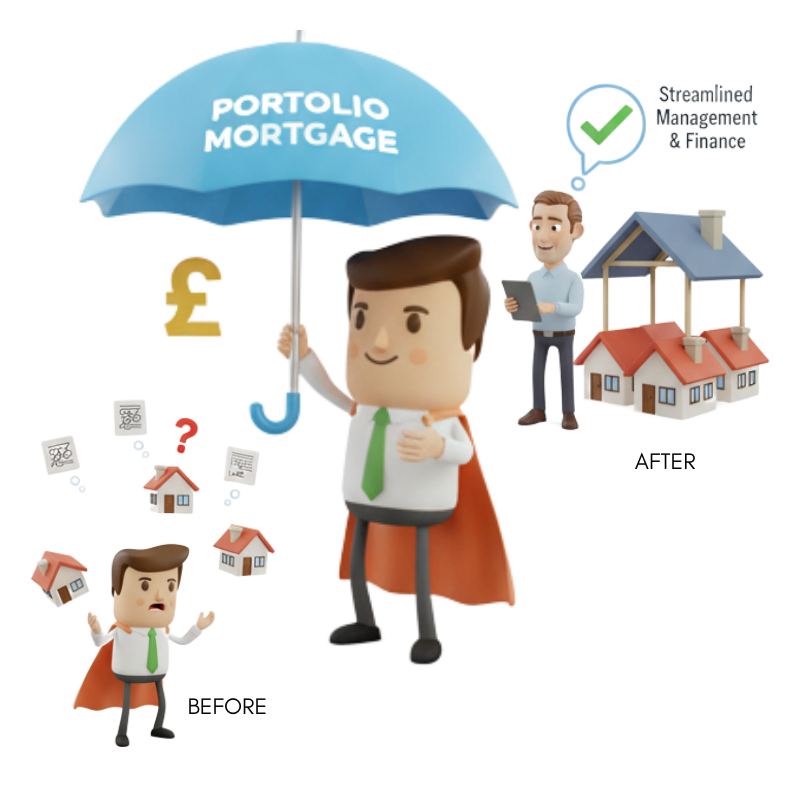
How a Mortgage Broker Can Help After a Buy-to-Let Mortgage Decline
Mortgage brokers can guide you through the process after a decline. They know the criteria of various lenders and can help you find the best ones for your situation.
Brokers can also help you improve your application. They will assist you with paperwork, advise on improving your credit score, and present your case in the best possible way.
In addition, mortgage brokers have access to exclusive deals that might not be available to the public. This can increase your chances of securing a better deal, even after a decline.
Frequently Asked Questions
Frequently Asked Questions: Declined Buy-to-Let Mortgage Applications
Why was my Buy-to-let mortgage application declined?
Can I reapply if my Buy-to-Let mortgage was declined?
Does a declined Buy-to-Let mortgage affect my credit score?
What rental income do lenders require for Buy-to-Let mortgages?
Can I get a Buy-to-Let mortgage with bad credit?
Will I need a higher deposit if my Buy-to-Let mortgage was declined?
Can I appeal a declined Buy-to-Let mortgage application?
Do lenders decline Buy-to-Let mortgages based on property type?
How can a mortgage broker help if my application is declined?
Is self-employment a common reason for a Buy-to-Let mortgage decline?
Can I switch lenders if my Buy-to-Let mortgage was declined?
What documents should I double-check to avoid a decline?
Client Testimonial
"We were feeling pretty frustrated after being turned down for a Buy to Let mortgage by our bank. Everything seemed to be going in circles; too many forms, not enough clarity, and no real explanation as to why we were declined. It left us doubting whether we could move forward with our investment plans.
A friend recommended Power Mortgages, and working with Manny was a completely different experience. He took the time to understand our situation properly, explained what went wrong with our previous application, and found a lender who was actually the right fit for us. What really impressed us was how personal the service felt, no generic advice, just clear guidance that was right for us. We'll definitely use Power Mortgages again."
Danyaal & Ayesha Malik